A Van Line's First Offer, a Nine Month Window, and the Point Where Settling Won
By Callum Fitzgerald·4 minute read
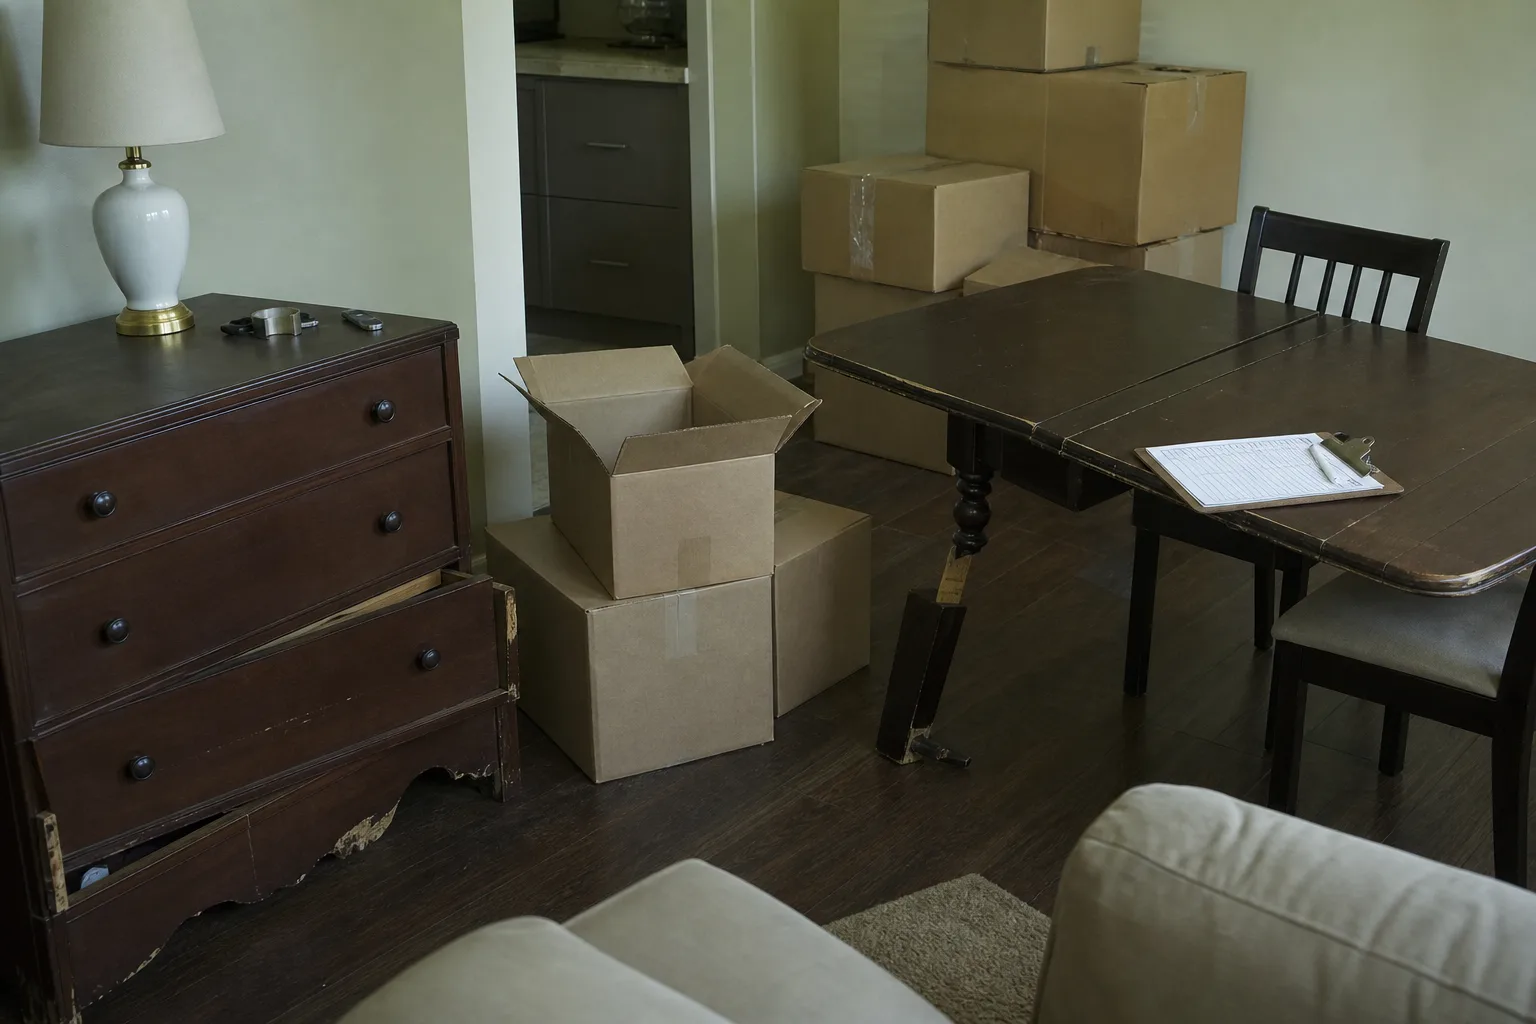
Law, September 16, 2026: The Barretts moved in late June, which is when almost everyone moves, and which is why the estimator who walked their house in May was booking three weeks out. The van line was a national carrier with a recognizable name on the trailer, a franchised agent at the origin, a different agent at the destination, and a driver who worked for neither of them in any way the family could easily describe. Two pieces arrived broken: a dining table with a cracked leaf support, and a bedroom dresser with a split back panel. The driver noted both on the inventory sheet before he left. That sheet, more than anything said afterward, is what made the next four months workable.
The checkbox in June that set the ceiling in October
Somewhere in the paperwork signed at origin, the household chose a valuation level, and that choice, not the price of the furniture, decided what the claim could ever be worth. Interstate carriers offer two basic levels: released value, which is included at no extra charge and settles damage by weight at sixty cents per pound per article, and full value protection, which costs more up front and obligates the carrier to repair, replace, or pay the value of the item. Under released value, a two hundred pound dresser is a hundred and twenty dollar dresser, whatever it cost. The Barretts had paid for full value protection. That single line item, added in June and forgotten by July, is the reason their October conversation was a negotiation rather than an announcement.
The clock that actually governs the file
Household goods moves across state lines are governed by federal regulation, and the Federal Motor Carrier Safety Administration, within the Department of Transportation, oversees the carriers that perform them. The timing is not a matter of company policy. A claim must generally be filed with the carrier within nine months of delivery, which sounds generous until a family unpacks the last boxes in September and finds a third damaged item. The carrier then has thirty days to acknowledge the claim in writing and one hundred twenty days to pay it, decline it, or explain in writing why it needs more time, with updates at regular intervals after that. The Barretts filed in mid-August. Acknowledgment came inside three weeks.
What the first offer was made of
The first offer arrived in early October and covered repair of the table, at a figure drawn from a repair vendor the carrier uses, and depreciation-adjusted cash for the dresser on the theory that the split panel was cosmetic. It was not an insult, and it was not the number. The family had three things the adjuster did not: the driver's own notation on the inventory, photographs taken the afternoon of delivery with the boxes still stacked behind the furniture, and a written estimate from a local furniture restorer who had seen the dresser in person and disagreed that the panel was cosmetic. Sending those three items, without argument attached, moved the file. The second offer covered full repair on both pieces.
Where pressing further stops buying anything
The gap that remained was the dining table's loss of value after repair, which the family put at a few hundred dollars and the carrier declined entirely. Interstate carriers are required to offer a neutral arbitration program for disputes of this kind, and they must tell you it exists and how to use it. The Barretts read the program description carefully. Arbitration would have been decided on documents, would have taken additional months, and would have turned on whether a competently repaired table is worth less than an undamaged one, a question on which their own restorer was politely noncommittal. The remaining money was real. It was also smaller than the effort of chasing it, and the household said so out loud before deciding.
The signals that told them the file had stopped moving
Three things changed between August and October, and then nothing changed again. The offer rose once on new evidence, the adjuster's letters shifted from questions to restatements, and the family ran out of documents the carrier had not already seen. That is the usual shape of it: a claim moves when you hand over something new and verifiable, and it stalls when your only remaining contribution is emphasis. Settling at that point is not surrender; it is recognizing that the leverage you had was documentary, that you have spent all of it, and that the next stage costs months to recover a sum you can already name.
The final invoice, and what it did not include
The restorer did both pieces in one visit in November, billed once, and the carrier's check cleared against that invoice with a release form attached. The release was broad, as releases are, and the family read it knowing that signing closed the file on the move entirely, including the third item found in September that they had folded into the claim in time. The full value protection premium, paid in June, had cost less than the repairs it produced. The delivery-day photographs cost nothing at all. Between them, they turned a four-month process into one with a knowable end and a bill that someone else paid.
Moving season ends and claim season begins, which means that a household delivering in June is usually negotiating in September and October, with the nine-month deadline sitting quietly ahead and the hundred and twenty day window running in the background. Knowing when to settle is mostly knowing which of those clocks is still working for you. When the evidence is spent and the offer covers the repair, take the check.